
The short answer: if a storm may have damaged your roof, get a professional inspection promptly, document everything with photos, file your claim, and work with a reputable local roofer who can meet your adjuster. Storm and hail damage is typically covered by homeowner’s insurance, but coverage depends on your policy, and acting quickly protects both your home and your claim.
Recognizing storm damage
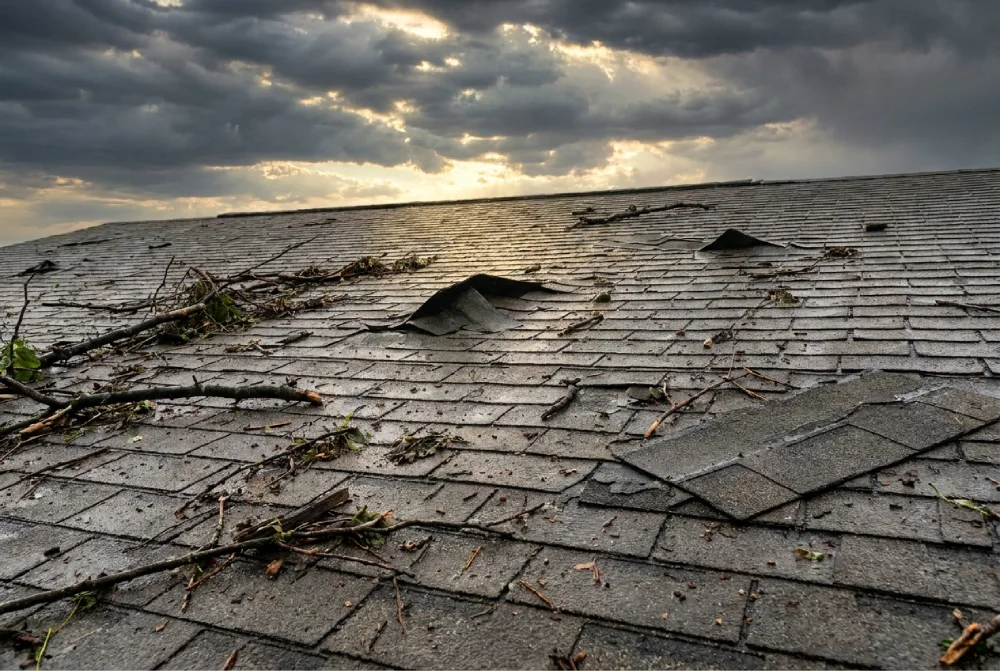
Some storm damage is obvious, missing shingles, a limb through the roof. But a lot of it is not. Hail in particular can bruise shingles, crack them, and knock off the protective granules in ways that are hard to see from the ground but shorten your roof’s life and lead to leaks months later. Signs to watch for after a storm:
- Missing, lifted, cracked, or creased shingles
- Granules collecting in gutters and downspouts
- Dents on metal roofing, vents, or flashing
- Dented gutters, screens, or other soft metal (a clue hail was significant)
- Water stains on ceilings or in the attic
- Debris or limbs on the roof
Why a professional inspection comes first
Because so much storm damage is subtle, a professional inspection is the right first step. A good roofer inspects the whole system, roof surface, flashing, vents, and gutters, and documents everything with photos. That record is what supports your insurance claim, and it is best gathered while the damage is fresh. Roof inspections.
How roof insurance claims generally work
Every policy and insurer is different, but the process usually looks like this:
- Inspection and documentation. A roofer assesses and photographs the damage.
- File your claim. You contact your insurer and open a claim.
- Adjuster visit. The insurer sends an adjuster to assess the damage. A reputable roofer can meet the adjuster at your home to help ensure the damage is fairly and fully assessed.
- Claim decision and scope. The insurer determines coverage and the scope of approved work.
- The work. Once the claim is settled, your roofer completes the repair or replacement.
A few honest cautions.
- No one can guarantee your claim outcome. Any roofer who promises to “get your insurance to pay” or to “waive your deductible” is a red flag. Covering or rebating a deductible is improper, and pressure tactics are a sign of a storm-chaser.
- Beware out-of-town crews. After big storms, crews flood the area, knock on doors, and often vanish before the work is right or the warranty means anything. Choose a local company that will be here next year.
- Act promptly, but not in a panic. Prompt documentation matters, but do not sign over your claim or rush into a contract under pressure.
What is and is not usually covered
Storm and hail damage is generally covered by homeowner’s insurance, while gradual wear, age, and lack of maintenance usually are not. This is also why a roofing workmanship warranty and storm insurance are two separate things: your workmanship warranty covers installation, while storms are an insurance matter.
We help you through it
BCI Roofing inspects and documents storm damage, meets your adjuster, and completes the work to a high standard, then we can rebuild your roof stronger as a FORTIFIED-credentialed contractor. Call (910) 922-2188 or request a free inspection.